Opinion | A $10 Billion Threat: How Exposed India Really May Be To Middle East's Oil Crisis
Every $10 increase in the price of Brent crude could widen India's current account deficit by roughly 0.3 to 0.4% of GDP, translating into over USD 10 billion in additional import expenditure.
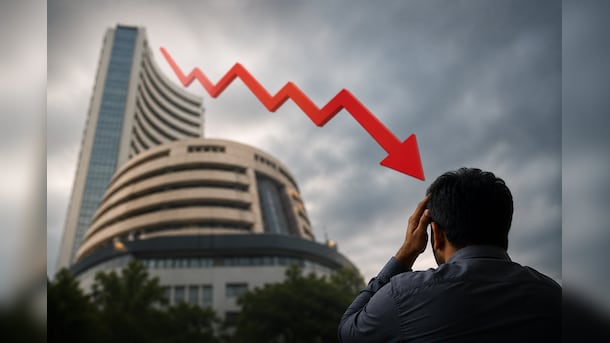
As the stock market bleeds, trade's stopped in major routes, interlinked businesses collapse, each nation's macroeconomic resilience is under a severe stress test, especially, when a country's energy system is deeply embedded in fragile global networks. The rapidly escalating conflict in West Asia triggered by the US-Israel power axis and the rising instability surrounding Iran's response, its blockade of the Strait of Hormuz in a few days, illustrates how quickly such disruptions travel from tanker routes to macroeconomic fundamentals.
For a major energy-importing economy like India, the macroeconomic shock does not remain limited to oil prices. It moves almost immediately through the balance of payments, financial markets, and corporate balance sheets. The most immediate transmission mechanism is the balance of payments. India relies on imports for over 85% of its crude oil requirements, making energy prices one of the most powerful external determinants of macroeconomic stability.
Empirical estimates suggest that every ten-dollar increase in the price of Brent crude widens India's current account deficit by roughly 0.3 to 0.4% of GDP, translating into over USD 10 billion in additional import expenditure.
What History Suggests
Energy shocks rarely occur in isolation. Periods of geopolitical uncertainty often trigger broader commodity movements and precautionary import behaviour. In early 2026, India's gold imports surged sharply as households and investors sought a hedge against global volatility. Combined with higher fertilizer imports and rising energy costs, this pushed the country's merchandise trade deficit to unusually elevated levels.
Before drawing parallels with earlier oil shocks, however, an important distinction must be made. The current disruption does not yet resemble the systemic energy crises of the past.
It's Different This Time
The scale of the price increase remains modest. Brent crude is trading around the eighty-dollar range, well below the levels reached during the Russia-Ukraine energy shock in 2022, when prices surged above USD 130 per barrel. Even in historical perspective, current prices fall within ranges that global markets have previously absorbed without triggering a full macroeconomic breakdown.
Equally important is the narrow scope of the disturbance. Earlier crises were marked by simultaneous surges across multiple energy markets. The inflationary spiral of 2021 and 2022 was driven by the simultaneous rise in oil, natural gas, coal, and electricity prices. Today's volatility is concentrated largely in crude oil and liquefied natural gas markets, preventing the broad-based energy inflation that defined previous crises.
The structure of global energy consumption has also evolved dramatically since the 1970s. At the time of the Arab oil embargo, petroleum accounted for nearly 25% of global electricity generation. Today, that share has fallen to less than 3%.
The Import Vulnerability
Yet the absence of a full energy crisis does not mean the macroeconomic consequences are mild. For energy-importing economies, even moderate oil shocks propagate quickly through domestic inflation dynamics.
Higher oil prices feed directly into retail inflation through transportation costs, energy inputs, and fertilizer-linked agricultural prices. A sustained increase of USD 10 to 15 dollars per barrel can add roughly thirty basis points to consumer price inflation, while shaving roughly twenty basis points off real GDP growth. This creates a textbook stagflation drag, importing inflationary pressures while suffocating domestic expansion.
This widening deficit places immediate depreciation pressure on the Rupee. To prevent a currency freefall and limit imported inflation, the Reserve Bank of India is forced to aggressively intervene using its foreign exchange reserves to mop up Rupees.
This massive intervention sucks immense amounts of Rupee liquidity out of the domestic banking system. Consequently, domestic borrowing costs spike for businesses and consumers alike. The dynamic creates a shadow tightening of monetary policy that chokes off credit growth, even if the central bank officially holds the repo rate steady.
Persistent inflation driven by these supply-side shocks also forces households to dip into their savings to maintain basic consumption levels. This reduces the pool of domestic capital available for investment, further constraining long-term economic growth.
The Point India May Be Missing
The narrative that India's economy resides in a resilient sweet spot relies heavily on the assumption of frictionless global trade. A prolonged paralysis of the Strait of Hormuz shatters that premise, exposing the structural limits of the nation's energy architecture. The Strait itself carries around one-fifth of global oil supplies and over 20 million barrels per day of petroleum flows, making it one of the world's most critical energy chokepoints. India's profound dependence on Gulf suppliers reveals that aggregate macroeconomic buffers are highly asymmetrical.
While strategic petroleum reserves offer a temporary cushion for crude, the lack of strategic storage for refined products leaves the domestic economy dangerously exposed to localized shocks.
However, the core threat remains macroeconomic stabilization. The true cost of an extended Hormuz closure is the sudden obsolescence of India's current strategic reserves and subsidy frameworks. Moving forward, policymakers must urgently rethink their strategic response to these vulnerabilities. This requires expanding the size and scope of strategic reserves to include essential fuels like LPG, aggressively diversifying toward Atlantic Basin crude, and building robust maritime security coordination with Gulf partners.
A logistical freeze in the Middle East does not merely slow Indian economic growth. It destabilizes the country's balance of payments and amplifies its external vulnerability, which demands a complete recalibration of how the nation insulates its macroeconomic stability from external geopolitical decay when uncertainty rises.
[Deepanshu Mohan is Professor of Economics and Dean, O.P. Jindal Global University. He is a Visiting Professor, London School of Economics and a Visiting Research Fellow at the University of Oxford. Ankur Singh is a Senior Research Assistant with Centre for New Economics Studies (CNES), O.P. Jindal Global University.]
Disclaimer: These are the personal opinions of the author
-
BJP Leader's Singer Wife, A Kabir Bhajan, And Some 'Jantar Mantar': How 15th Century Saint Entered 2026 Row

A video of Sivasri Skandaprasad's singing performance went viral, interpreted as a dig at protests at Delhi's Jantar Mantar. What she's singing is actually attributed to the saint-poet Kabir, and he did not really mean that particular "jantar mantar". He meant something far more profound.
-
Opinion | Sardar Patel, And The Art Of Holding A Nation Together
A true Gandhian, he reminded his countrymen that gaining freedom from foreign rule was merely the first step; true internal Swaraj required much, much more.
-
Opinion | How India Is Making Its Stock Market An Expensive Place To Invest
FPIs sold Rs 1.66 lakh crore of Indian equities in 2025 and a record Rs 3.08 lakh crore in 2026 through October 12. Foreign ownership of the Indian market is at a 15-year low
-
Jail Is No Bar: How Gangsters Call The Shots From Inside Prisons
Jail can become a safe haven from enemies, a recruitment ground for fresh gang members and, in some cases, a command centre for criminal operations
-
From King Edward III To Neha Bora, A 1361 Law Lives On In 'Peace Bonds': NDTV Explains
CJP leaders Abhijeet Dipke, Saurav Das, and Ashutosh Ranka signed peace bonds; two of them even faced jail over an alleged breach, while AISA's Neha Bora questioned such a bond's very logic. Here's what a peace bond is, and what the questions are.
-
Air Force Golf Course Near PM House Closed. How This Land Has Seen Many Turns Of History
The Air Force Sports Complex, which includes the golf course, is the latest property near the Prime Minister's residence set to be taken back this year, as the land is owned by ministries.
-
Opinion | How A Poland 'Experiment' Could Change India's Defence Industry
Europe is spending billions on arms in a historic rearmament drive. Indian firms can cash in. But there's a catch
-
Opinion | The Muslim World Is Seeing An Unexpected 'Experiment' - In Kazakhstan
The country has a long history of using mediation to mitigate conflict; now, it has added another, much-wanted dimension to it.